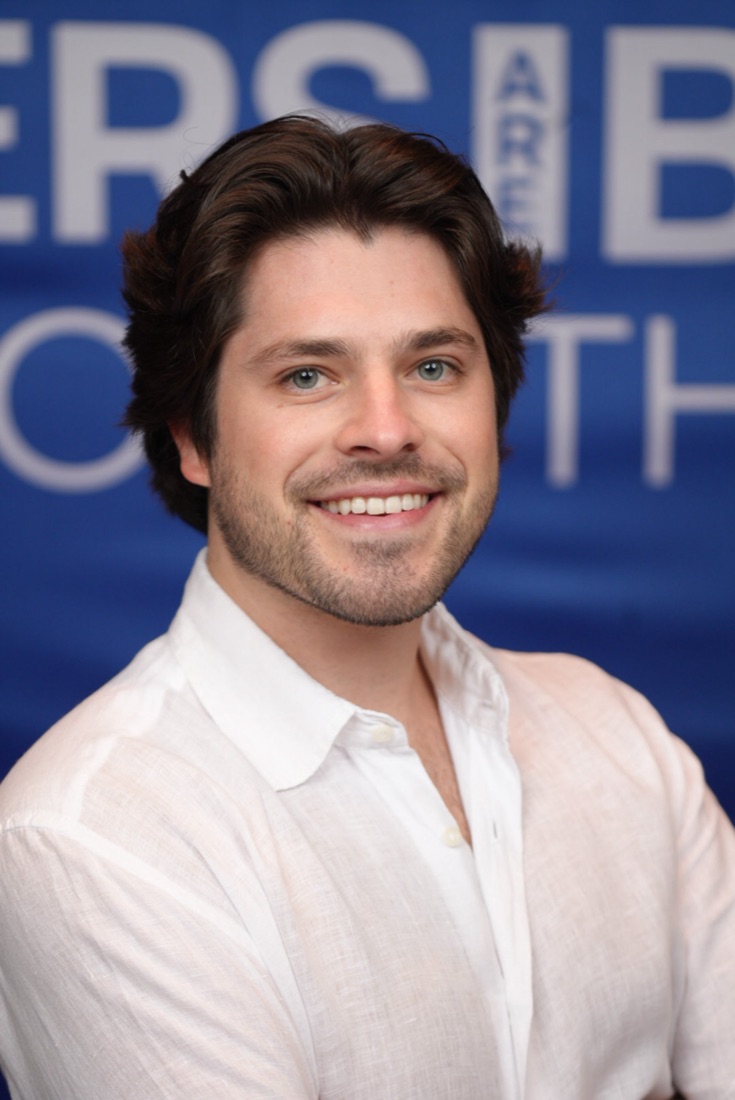
Southern California roots.
White-glove service.
I was born and raised in Los Angeles, so Southern California real estate is home turf. Whether you’re buying your first home, moving up or tapping your equity, I’ll match you with the right loan, from conventional to jumbo, and move fast enough to win in a competitive market.
Case-Shiller index,
High-balance pricing up to this amount, then jumbo.
Your home deserves careful hands.
- High-balance & jumbo expertise. Conforming loans go up to $1,249,125 in Orange County. Beyond that, I shop jumbo lenders head to head.
- Built for business owners. Bank statement, P&L and asset-based loans for entrepreneurs whose tax returns don’t tell the whole story.
- Equity strategies. Many OC homeowners have huge equity and a low rate. HELOCs and home equity loans unlock it without giving up that rate.
- Mello-Roos, HOA & insurance. Your payment includes the real costs of newer Irvine-area communities and today’s California insurance market.
Areas I serve in Orange County
Irvine · Newport Beach · Newport Coast · Costa Mesa · Huntington Beach · Laguna Beach · Laguna Niguel · Dana Point · San Clemente · Mission Viejo · Lake Forest · Tustin · Orange · Anaheim · Anaheim Hills · Yorba Linda · Fullerton · Brea · Ladera Ranch · Rancho Santa Margarita · Seal Beach
What OC clients ask.
Who is a good mortgage broker in Orange County?
Choose a broker who compares many lenders, including jumbo and high-balance options, and handles every kind of income well. Thomas Von Der Ahe (NMLS #2017782) with the VDA Mortgage Team at Edge Home Finance shops 150+ lenders and specializes in creative financing and fast, white-glove closings.
What is the 2026 conforming loan limit in Orange County?
$1,249,125 for a single-family home, the federal high-cost ceiling. Loans between the national baseline ($832,750) and that limit are called “high-balance” conforming loans. Above it, you’ll need a jumbo loan.
How much down do I need for a jumbo loan?
Many jumbo programs start around 10% down for strong borrowers, with 20% unlocking the best pricing. Interest-only and bank statement jumbo options are available too.
Can I keep my low rate and still tap my equity?
Yes. A HELOC or home equity loan sits behind your existing first mortgage, so your low rate stays put. It’s often the smartest way to fund a remodel, an ADU or an investment.
Do you help with divorce buyouts in California?
Yes. California is a community property state, so buyouts come up often. I coordinate with your attorney to structure the refinance and buyout cleanly, often with better pricing than a standard cash-out.
Don’t take my word for it.
Real clients, real closings. My newest Google reviews show up here automatically.
★ · 19 Google reviewsLet’s find your actual rate and payment.
Averages are just a starting point. Your actual rate depends on your credit, property and goals. Book a quick call and I’ll shop 150+ lenders for you.